New VAT Late Submission, Late Payment Penalties and Interest Charges

As part of HMRC’s ambition to become a modern, trusted tax authority, it is changing the way penalties are issued for submitting late VAT returns and paying VAT late, which will affect all VAT registered businesses from 1 January 2023.

For  VAT periods starting on or after 1 January 2023, HMRC is replacing the default surcharge with separate penalties for late returns and late payment of VAT.  At the same time, HMRC is introducing a new approach to VAT interest.​

If you submit your VAT return late

Late submission penalties will work on a points-based system. For each VAT Return you submit late you will receive one late submission penalty point. Once a penalty threshold is reached, you will receive a £200 penalty and a further £200 penalty for each subsequent late submission.

The late submission penalty points threshold will vary according to your submission frequency.

Submission frequency Penalty points threshold Period of compliance
Annually 2 24 months
Quarterly 4 12 months
Monthly 5 6 months

You will be able to reset your points back to zero if you:

  • submit your returns on or before the due date for your period of compliance — this will be based on your submission frequency
  • make sure all outstanding returns due for the previous 24 months have been received by HMRC

The new points–based system for late submissions is designed to be more lenient for the occasional slip–up, whilst still penalising those who repeatedly fail to comply. Late payment penalties will be charged at different rates based on when payment is received. This means the penalty is more proportionate to the length of time a payment is outstanding – the sooner you pay, the lower the penalty.​

HMRC is also introducing late payment interest, which means that you’ll be charged interest from the date your payment is overdue, until the date you pay in full. HMRC is discontinuing repayment supplement and instead will be introducing repayment interest. Customers who make a repayment claim will be paid repayment interest from the day after the due date, or the date of the submission (whichever is later), to the date the repayment is made.

By introducing these changes, HMRC is aiming to incentivise businesses to file their returns on time and pay their VAT on time. This will make it easier for businesses to understand their obligations and help to ensure that HMRC continues to be a modern, trusted tax authority.

For more information, see the HMRC guidance on how to prepare for upcoming changes to VAT penalties and VAT interest charges.

Speak to us if you need help preparting and submissing your VAT returns on time. Our experienced bookkeeping team will be happy to help.

Xero Efficiency Tips

Xero is a cloud-based accounting software designed to help businesses manage their finances more efficiently. The software is user-friendly and offers a wide range of features making it easy for businesses to track their income and expenses, create invoices, manage inventory, and generate reports.

One of the key benefits of using Xero is its ability to save time and reduce the amount of manual work involved in managing finances. With Xero, businesses can automate many of the tedious and time-consuming tasks associated with accounting, such as reconciling bank accounts and generating reports. This allows businesses to focus on more important tasks, such as growing their business and serving their customers.

Another benefit of using Xero is its ability to provide real-time financial information. With Xero, businesses can access their financial data in real-time, which allows them to make informed decisions about their finances and ensure that they are on track to meet their goals. This real-time information can also be shared with other members of the business, such as accountants and investors, which can help to improve collaboration and communication within the organization.

Xero also offers a range of tools and resources that can help businesses to improve their efficiency. For example, the software includes features such as the ability to track inventory, create purchase orders, and manage bills and expenses. This allows businesses to easily manage their finances and stay organized, which can help to reduce errors and improve overall efficiency.

In addition to these features, Xero also offers a range of integrations with other popular business tools and software. This allows businesses to connect Xero with other systems and platforms, such as point-of-sale systems and ecommerce platforms, which can help to improve the overall efficiency of their operations. For example, businesses can use Xero to automatically import their sales data from an ecommerce platform, which can save time and reduce the risk of errors.


In summary, there are several ways to use Xero more efficiently and effectively, including the following tips:

  1. Import your bank statements directly into Xero to save time and avoid errors.
  2. Use Xero’s mobile app to manage your finances on the go.
  3. Use Xero’s built-in reports to get a clear picture of your business’s financial health.
  4. Set up automatic reminders for invoices and bills to avoid late payments.
  5. Use Xero’s collaboration tools to work with your accountant or bookkeeper in real-time.
  6. Take advantage of Xero’s integrations with other business tools, such as online payment systems and inventory management software.

In addition to the tips mentioned earlier, there are several other ways to use Xero more efficiently:

  1. Use Xero’s recurring invoices feature to automatically generate and send invoices on a regular schedule.
  2. Use Xero’s multi-currency support to manage transactions in multiple currencies.
  3. Use Xero’s project tracking feature to track time and expenses for specific projects.
  4. Use Xero’s inventory management tools to track stock levels and generate purchase orders.
  5. Use Xero’s payment gateway integration to accept online payments directly from invoices.

Overall, Xero is a powerful and efficient tool for businesses looking to manage their finances more effectively. The software’s user-friendly interface, real-time financial information, and range of features and integrations make it easy for businesses to save time and improve their efficiency. By using Xero, businesses can focus on growing their business and serving their customers, rather than spending time on tedious and time-consuming accounting tasks.

Talk to our experienced bookkeeping team if you want to explore Xero and it’s additional features for your business or would like someone to help you with keeping your accounts updated and relevant.

Business Finance Options

Throughout the cycle of a business, there is often a need for some additional cashflow to support business growth. Ever assumed that only struggling businesses need extra finance? Securing cashflow finance for your business can actually mean the opposite.

Business Loans can be used to fund the growth and expansion of a business, the purchase of a new premises, additional stock, recruitment or simply to provide some extra funds in the bank to offer some peace of mind.

What different types of business loans are available?

The most common types of business finance are Business Loans, Invoice Finance, Asset Finance and Property Finance. There are also many other alternative finance options such as Revolving Credit Facilities, VAT Loans and Merchant Cash Advance.

Why would a business need finance?

There are lots of reasons a business may choose to source additional funding. Here are some examples of how the different products work, and the benefits to the business:

  • Business Loans – often used for cashflow, expansion and growth. This loan would be a fixed amount over a fixed term, and many lenders don’t charge an early repayment fee if the loan amount is settled prior to the end of the term.
  • Invoice Finance – a way to improve cashflow when you have 30/60/90 day invoice terms. For example, a construction firm who has to pay out for materials and labour before their client clears the invoice, which heavily impacts cashflow. With Invoice Finance, the construction firm could borrow up to 90% of the invoice amount in advance, automatically paying the balance back when their client pays their invoice.
  • Property Finance – covers a variety of products including Commercial Mortgages, Bridging Loans and Development Loans. A property developer looking to fund their next project could utilise property finance to purchase the property or land and cover all projected costs.
  • Asset Finance – a facility which allows businesses to purchase new assets, including vehicles, plant, machinery and hardware, without using cash from their bank. You can spread the cost of the asset over a fixed term with a fixed interest rate.
  • Revolving Credit Facility – works in a similar way to an overdraft and allows you to withdraw, repay and withdraw again, whenever your business needs a cashflow injection. You only pay interest on what you use of the facility. A flexible solution which grows with your business.
  • Merchant Cash Advance – an additional financing solution for businesses such as retail, leisure or hospitality who take payments via a card terminal. You can borrow against forecasted revenue and pay back using the transactions taken, either in person or online.
  • VAT Loans – a type of borrowing specifically to spread the cost of an unexpected VAT bill. A VAT Loan can be arranged prior to the VAT being due, or can be put in place shortly after the VAT has been paid, helping to maintain cashflow within the business.

How does a business owner know if they are eligible to apply for a business loan and how much could they borrow?

A businesses eligibility is based on lots of factors including company trading history, the directors’ personal circumstances and company financials. A business would typically need a minimum of 3 months trading history, but the longer you’ve been trading and the more evidence you can provide of your affordability, the more attractive your business becomes to a lender which is then reflected in the rates, amount and term offered.

How can a company apply for a business loan?

The first place a business will usually go for a loan is their bank. The risk appetite of a bank is low, so applications can be rejected unless the business is extremely favourable. If your bank says no, you can then approach an alternative lender directly, or via a finance broker. A broker will use their experience to match you with the most suitable finance product, and as they generally work with a large panel of lenders, they have lots of options to choose from.

How does a business owner know what type of business loan is right for them?

There are so many different products in the market, so it’s hard to know where to start. Having a conversation with your bank or a finance broker is a great starting point so they can understand your requirements, and suggest some options that suit your needs and that you would be eligible for.

Where would a start-up business look for funding?

If you are a start-up or have been trading for less than 3 years, you may be eligible for a British Business Bank loan, which are backed by the government. You can apply online at www.startuploans.co.uk and they will assess your application along with your business plan, cashflow forecasts and directors experience in order to make a decision. You may also be able to raise funds via private investors or crowd funding, and your Local Enterprise Partnership should be able to offer advice on any grants and funding that you may be eligible for within your local business community.

When is the right time to start thinking about business finance?

Often business owners only start to think about business finance when they need it, by this time your eligibility may have suffered, or there may be limited options available to you. By forecasting your cashflow for the year ahead, you may be able to identify any opportunities that may require additional funding, for example an upcoming VAT bill, dips in revenue due to seasonal trading or planned expansion costs. By applying when your finances are healthy, you are ensuring you have as many options available to you as possible, on the best terms.


Grange Business Finance are an FCA approved commercial finance brokerage based in Suffolk, sourcing cashflow solutions for your business. For more information on their services, visit www.grangebusinessfinance.co.uk.


3 Fail-Safe Business Growth Ideas

There isn’t a small to medium sized business that isn’t looking to manageably scale and grow their business. Yet growing a business can be difficult for many companies. If nothing else, attempting to work on the business whilst you’re working in it, is exhausting. However, we have three fail-safe ideas which we always tell our clients to follow if they want to start making meaningful differences in growing their company.

Simple Business Growth Ideas for SMEs


  1. Put Your Prices Up!

The majority of clients rarely think to put their prices up, or worse — feel like they can’t. However, everyone else is putting their prices up; so of course, you must also. Price is often tied up with concern over a. worth or b. demand. The truth is, if people want your product or service, they will pay for it. If you are competitive and professional, why shouldn’t you expect to charge the correct price?

Undervaluing and underselling a product or service is not only detrimental to our mental states as we start to believe our worth is akin to the charge amount, but also terrible for our industries. Repeatedly I witness horrifically low hourly rates on agency sites. Not only are these personally unsustainable, but it devalues the sector as a whole. At some point, the people who are initially selling their work for such low rates have to put their costs up to survive, then guess what? Clients will look for the cheaper option – pushing these guys out of the sector as they can no longer afford to remain with these sorts of clients. Very simply, cost your work properly and charge what is required to offer a first-class service or product, the right people or companies will pay for the best. It is these clients or customers you should be looking to align your company alongside.

How to easily raise your prices

Try answering these questions:

  • Are you charging enough?
  • How do you measure your profit margin on each sale you make?
  • What does a 5% increase in sale price do to your profit margin?

Now try two simple exercises:

  • Look at all your services and simply add £50 to them. What does that increase look like? What difference does that make?
  • Now consider your clients: if you have 10 clients bringing in £1,000 per month each, put £50 on each (5% increase). What would £500 extra per month mean to you? See how much more you can earn by adding a slightly greater increase.
  1. Sort out your sales and marketing!

Yup, if no one knows you exist how do you expect to sell anything? Marketing is essential for bringing in new leads to convert into clients or customers.

Have you ever considered how many new clients or customers you actually need to earn the money you’re looking to achieve?

Marketing consultant and founder of Sasa.Marketing, Cat Bowyer, offers three genuinely helpful pieces of advice to companies looking to get better noticed:

A. Do you really know who your customer is?

  • Do you know their motives?
  • What are their communication channels?
  • What concerns do they have?
  • What size are their budgets?

Understanding your customer will ensure you’re investing your marketing spend in the right places.

B. Make sure your marketing objectives reflect your business objectives. Are you looking to achieve growth through new customers, or growth through increased sales per customer? What about your profit margin and sales relationship? Do you have a high margin and low sales or a low margin but high sales?

C. Websites and social media content are great, but you still need to let people know you’re online. Otherwise it’s like having a box of leaflets under the desk. Make sure there’s a mix of campaign and brand awareness activity.

From a bookkeeper’s perspective we look at the figures involved in marketing from a time and value ratio.

  • Do you know your conversion rates? (The conversion rate is the percentage of new leads who take a desired action and become paying customer.)
  • How many leads do you need to generate, so they eventually convert into the desired number of clients or customers?

For example, conversion rate of new leads to paying customers is 5% and you would love to gain two new clients in a month. How many leads do you need to generate? The answer is 40 new leads, which at 5% conversion rate will secure you two new clients.

Marketing is a numbers game! The more people you attract, the more customers or clients you’ll retain! The greater your marketing efforts, the greater your gain.

  1. Capacity

To improve capacity, it is essential your organisation runs efficiently. Rather than taking on more costly staff members, place in better systems and processes that actually work to reduce labour time in all departments.

  • Train your current work force with your new systemisation to effectively utilise your current team, before looking to employ more staff to cope with an increase in demand.
  • To systemise your organisation, you will need a plan. It’s essential you understand your figures and have a visualisation of the profit you require to achieve the kind of growth you’re looking to make. If the figures and goals aren’t attainable or tangible, how do you expect to get great results?
  • To get an idea of how to create a financial model and plan that will work for you, read our article: Financial Clarity – How To Sleep At Night.


Business growth doesn’t have to be confusing:

  1. Create a plan
  2. Put your prices up
  3. Market yourself
  4. Improve your efficiency.

However, if you want to chat through these ideas or look at figures you can achieve with a professional bookkeeper, get in touch! Call 01206 700 252 or email hello@clouditbookkeeping.co.uk

How To Save For Tax Payments

In 1716 Christopher Bullock wrote in his comedy play The Cobbler of Preston, “Tis impossible to be sure of anything but Death and Taxes”. Whilst tricky to argue with, it’s not a terribly inspiring thought!

If we’re honest, the death part is not really in our realm of services. But understanding tax and making it less scary, is definitely where we help businesses!

To get on top of tax payments there is only one simple trick you need to know: plan and save!

I know, you’re thinking that’s easier said than done, and of course it is! If it was so super simple, nobody would ever find themselves worrying about how to pay their next tax bill.

However, all is not lost! This article explains the simple steps you can take to easily save and pay your tax bills, keep on top of your ins and outs, and maybe if you’re lucky — have some money left in reserves to put towards your dividends!

Cloudit Bookkeeping’s simple steps to saving for tax

  1. How much will you pay in tax?

Before beginning to work out how much you can save, you first need to establish how much you estimate to pay in tax each year.  This depends entirely on your business structure: are you self-employed (sole trader or partner in a partnership), or is your company limited? Limited companies have to pay what is called corporation tax. This is charged at a flat rate percentage (check the percentage applicable in that year, but in 2021-2022 this is 19%) on taxable profits. If you’re self-employed things get a little more complicated as there are various different tax rates which kick in at different tiers, plus national insurance and student loan repayments.

Limited companies

If your company is limited, you’ll need to pay your tax bill nine months and one day after your year end. Corporation tax must be paid on both your company’s profits and on any gains you made from selling assets that increased in value.

If you’re keeping your accounts up to date, it’s most likely you have a rough idea of how much net income you earn each month. You’ll be paying set percentage on your profits — the money you make in that accounting period, minus overheads and allowable expenses. It’s worth knowing that any expense your company incurs for the running ‘wholly, exclusively and necessarily’ of the business can be deducted from your company’s profits, before you pay tax. Expenses include:

  • Goods bought for resale
  • Purchase of materials
  • Freelancer costs
  • Salaries of all employees
  • Employers’ National Insurance Contributions (NICs)
  • Employer pension contributions
  • Business insurance
  • Business-related travel and accommodation
  • Office running costs
  • Accountancy costs

There are other expenses, but these are the main ones. Sadly, equipment and plant you buy and keep for the business cannot be claimed, as these are considered capital assets.

Once you’ve looked at how much you earn each month and have considered expenses and any tax reliefs you may be entitled to, you can then estimate the corporation tax amount you need to save for each month at the current tax rate.

Self-employed, sole traders and partners in a partnership

If you’re self-employed you’re required to pay your Self Assessment tax bill, Income Tax and National Insurance Contributions on your business profits, after deductions for expenses. You need to know these figures before you can start saving for your tax bill.

Our advice? Use HMRC’s self-employed ready reckoner to help you budget for your Self Assessment tax bill. (Yup, they’re trying to help you pay your taxes!)

Here you simply place in your estimated weekly or monthly profit to get an idea of how much Income Tax, Class 2 and Class 4 National Insurance you’ll be asked to pay. However, if you need to make payments on account, these are not included in this tool. The tool also assumes you have no other taxable income and receive the standard personal allowance.

  1. Accounts

Next, open two current accounts. One will be for income, the other for expenses.

  1. Savings accounts

Once you’ve opened the current accounts, you also need to open two savings accounts: one you will use to save for your tax, the other for your reserves.

  1. Expenses

How much do your expenses cost you each month? Work out every cost to your business from business rent and staff payments to stationary bills and water bills. Now you can calculate how much income you need to move into your expenses account to ensure your monthly bills are paid.

  1. Tax

Go back to your estimated figures you worked out for your tax and now calculate how much income needs to be moved into your tax savings account each month to ensure there’s enough to pay HMRC.

  1. Reserves

Whatever is left, gets moved into your reserves account to pay your dividends. This can also be your pot for expensive equipment required in the future and other big purchases.


Ta-dah! Saving for tax made simple! For those of you who are up-to-date with your accounts, payments can be made twice a month, but this is only possible if you have good record keeping and a great bookkeeper.

If, after reading this article, you’re still not entirely sure how to begin the process of sensibly saving each month, just ring Cloudit Bookkeeping!  We’re here to make sure businesses not only succeed but thrive!

Don’t let tax get you down; there are always ways to help businesses cope and a great bookkeeper is one of the best ways of helping yourself. Please call and we will assist in helping you remove the fear of future tax payments.

Financial Clarity – How To Sleep At Night

So, what’s stopping you from sleeping soundly? I would say like a baby, but we all know they sleep terribly …

Lying awake at night, with a thousand thoughts racing around your mind is a horrible state to find yourself. It leaves you exhausted and cranky with anxiety slowly clawing at your thoughts.

This is no way to function at the best of times, let alone when you’re attempting to navigate your business through financial and politically tricky times. As a business owner there can be many reasons sleep evades you.

Common business concerns often include:

  • Loss of clients — are customers leaving your services, creating a financial deficit?
  • Stagnation — is your business struggling to grow or move forward in direction?
  • Denial — admit it, are you in full control of your accounts?
  • Overheads — can you cover your business overheads and reliably pay your staff?
  • Income — are you struggling to personally earn enough to live on?

How to start taking control of your business

If any of the above worries resonate, it’s not surprising you’re finding it tough to sleep at night. Any of these concerns are difficult to know how to overcome. It often feels like the wood and the trees are one, and the light is never going to show at the end of a dark tunnel.

However, there are pragmatic solutions. Try answering these simple questions:

  1. How much money do you want to take home each month after tax?
  2. Where do you want your business to head?
  3. How are you going to reach your goal?

Financial Planning and Modelling

Once you’ve answered the above, it’s time to work backwards! How are you going to achieve your objectives?

If you want to feel in control of your business and profit, you need to make informed decisions based from your financial data. A financial plan and model helps you work out how much money you need, your expenses and what sources of income are available. In other words: a financial model helps a business budget, forecast and plan. It keeps companies in control of their business and finances, so they know they’re on track. And if they’re not — why they’re not on track so they can fix that problem.

What is a financial model?

Essentially it involves creating a spreadsheet (don’t groan – they don’t have to be terrible!) to act as a representation of some, or all of your business operations.

  • A model can be used as a decision-making tool. It can assist in forecasting business decisions as you will better understand how much or how little money you have, or when more revenue will be coming in so you can invest, spend or save accordingly
  • Financial plans can be used in strategic planning, cash flow analysis, sensitivity analysis or appraisal
  • Models help estimate the value of your business
  • A model is useful if you are looking to compare yourself with competitors
  • They are very handy when it comes to selling a business

Considerations for a financial model

On a spreadsheet you need to add your business assumptions – these are educated guesses based from your historical data: numbers, trends, external conditions, industry and market. It’s important to consider situations or challenges that may arise and place these into your model to help plan for unforeseen eventualities.

Ideally you need to create a model which helps you understand how to plan for:

  • Working capital: How much revenue do you need to make to support your business after paying out for your direct costs and operation costs?
  • Revenue: Is the business continuing on the same trajectory as previous years? This helps plan when and how payments occur, whether prices are correct, how and when customers buy and areas of business stagnation
  • Financial statements: Forecasting of financial statements helps with talking to investors, banks, auditors etc
  • Growth margin: How much money goes towards delivering your product or service and how much is left over? This helps you plan to successfully develop your company
  • Increase in demand: Do you have the manpower or software capabilities to cope?
  • Operational expense: How much does it cost you to operate as a business? How much does each area cost e.g. admin, marketing, software etc?
  • Significant decline: Look at why a product or service is no longer popular and use this to make an informed decision to find a successful solution

We know it may seem a tad daunting, especially if you have a lot to focus on, but believe us when we say how important a great financial modelling plan is to a business.

If you don’t know where to start, or just want to talk things through, please give us a call.

As cloud-based bookkeepers, financial planning is just one of the many services we offer, so chat to us and we can help you get the sleep you dream of achieving.

Call 01206 700 252 or email hello@clouditbookkeeping.co.uk and take control of your business finances.

Great finances = great sleep!

Spring Statement 2022

A detailed round-up of 2022 Spring Statement and changes coming up in the 2022-2023 tax year is this downloadable PDF prepared by The Institute of Certified Bookkeepers.

Click the link below to download your copy:

Spring_Statement_2022

3 Lessons Digital Agency Owners Can Learn from Nick Suckley?

The book “Start. Scale. Sell. 75 Lessons for Business Success” arrived on Friday morning and I have finished reading it by Sunday. The book just flows and is an easy read with concise lessons and examples. I believe any agency owner reading this would relate to most lessons Nick Suckley learned building and selling Media21 and Agenda21. I have picked out 3 that hit the cord the most with me being involved in helping digital agency owners manage and plan their financial side.

What can you, Digital Agency owner, learn from Nick Suckley’s experience?

  1. Measure your KPIs but don’t overcomplicate. Simplicity is key if you want to understand and use your numbers. The list of key performance indicators Nick uses is:
  • Pipeline – number and size of potential customers. If you do not have a sales strategy or there is no real sales pipeline, this will hurt the business most in the long run. You cannot leave new business to luck or referrals. This is unsustainable if you wish to grow. Imagine your best earning client decided to bring it all in-house or move the service you provide to another agency which usual mean you receive an email saying “we are bringing all our digital marketing under one roof and agency XYZ can do it all”. New business is the top 1 reason agency owners are stressed and anxious. Having data on sales pipeline will give you clarity and focus.
  • Pitch-to-win ratio – how many potential clients you converted via pitch or proposal. This is important as it will give you an understanding if your pitch material works and where you need to make changes. Correct positioning can help here too.
  • Billings per head – measure how productive your team is and if you are over or under servicing clients. The more efficient your team can be the more billings per head you can have.
  • Income-to-salary ratio – measure how profitable and productive the company is. If this ratio is too high you need to cut salary costs or increase your billings.
  • Gross profit margin – how good you are at charging clients.
  • Net profit margin – how profitable you are.
  1. Boost profitability – use the right tools. Nick calls this Profit Improvement Programme (PIP). You need to understand how each area of your business is generating income and what are the costs associated with it. Track each service you offer and associated team’s Profit and Loss (P&L). You might have media, paid search, SEO, social, affiliates and analytics services. You would match income with team costs for that service and any other associated expenditure. This will give you the profitability for each service area you provide. Nick has the Golden Rule which each team leader has to follow. This is – staff cost cannot be more than 50% of the income generated. If you follow this rule, you will have enough left for the general overheads and your own pay. Get this right and you will see great improvement in your net profit margin.
  2. Never make a loss. This is a tough but most important rule in my view. Nick Suckley argues that by not making a loss you do not lose control. Making decisions quickly when times are tough, cutting costs and staff will save your business. These are the toughest decisions for any owner but can mean survival or going under. That’s why having up-to-date and accurate financial information will make a difference and provide the data you need to make those vital decisions. You will have the gut feeling that things need to change, or things are not going quite right. Having your financial reports in good shape will help you understand the situation better.

What can you do right now to make a difference to your business?

Take these 3 steps today and you will be on the path to success:

  1. Measure, measure, measure. Decide on your KPIs, measure and report on them at least monthly. You will need to track staff hours spent on client work, service team P&L, sales pipeline and anything else you decide is vital in making business decisions. Start with simple Excel spreadsheet and build from there. You don’t need to overcomplicate it.
  2. Analyse your management reports monthly. Review your accounting function and make sure you have accurate data at least monthly. If you do not have management reports, then look at your P&L and Balance Sheet as a minimum.
  3. Set net profit percentage you want to achieve and maintain. Do everything you can to keep it above this level. Paying yourself is the number one priority.

If you are not sure where to start, we can help you get started and support your agency with providing accurate and up-to-date accounts information, reports and tracking. Get in touch with us today.


6 Reasons your bookkeeper is harming your business

Whether your bookkeeper is someone you have employed years ago, maybe it’s the admin assistant, or even your wife or mother in law, you need to be confident that they are doing a good job and looking after your business’ bottom line. A competent bookkeeper could be the difference between helping your business grow or letting it spiral out of control with mounting costs and decreasing margins.

As a busy business owner, you have plenty of other responsibilities that come with running your business and you might not know if your bookkeeper is taking you to the cleaners. The stories we year about bookkeepers defrauding hundreds of thousands of pounds from the businesses they work for and spend it on nice cars, expensive holiday and designer clothes. And these are the ones that got caught and were sent to prison!

How do you know what good bookkeeping actually looks like, let alone spot the warning signs that your bookkeeper is bad at their job and hurting your business?

To help, we’ve put together this list of tell-tale signs to help you determine if you’ve hired a bad bookkeeper who is harming your business or one worth keeping.

  1. They’re not qualified and not backed by professional body

Anyone can say that they are a bookkeeper just because they can enter invoices into your accounting system. However, bookkeeping is much more than just data entry. Someone without formal training can create chaos and confusion with the figures in your accounts, make VAT or PAYE errors and give you wrong information which you then use to make business decisions. To avoid hiring a bookkeeper that can’t do the job and do it well always check whether they have bookkeeping qualifications such as The Institute of Certified Bookkeepers (ICB) or Association of Accounting Technicians (AAT). A qualified bookkeeper would have certification and backing of their professional body and would have to adhere to professional standards set by them too.

What you can do: Before hiring the bookkeeper ask to see their training certificates or practice licence. If they do not have formal qualifications, you would have to assess if their experience is extensive enough to support your business appropriately.


  1. They don’t understand basic bookkeeping terminology

Your bookkeeper should know standard bookkeeping terms, including double-entry bookkeeping, cash and accrual basis, aged debtors/creditors, assets, liabilities, journals and so on. This relates to point 1 above too. Worryingly, we have spoken to other ‘bookkeepers’ who didn’t know what ‘reconciliation’ meant and also some have never seen or entered a journal. Lack of understanding of these terms will reflect in the basic bookkeeping entries and in turn the overall picture of the business’ financial position. One of the major jobs we do when taking over clients books from other bookkeepers is untangling their accounts by correcting wrong postings of payroll costs, VAT and PAYE liabilities, fixed assets and simple duplication of costs.

What you can do: Speak to your bookkeeper using the terms you want them to use. If they don’t use the correct terminology and it remains an issue, consider replacing them. A competent bookkeeper must be able to talk the talk.


  1. They are always behind on the books

Your business can’t grow if your books are always behind and you are forever catching up. You need to have correct and up-to-date information when you are making business decisions, such as how much can you spend on marketing, can you hire another person, can you find savings if you moved office – to name a few. Things can come up to cause delays, just as they do with any job, but a good bookkeeper looks for opportunities to get caught up and maintaining deadlines.

What you can do: Set clear deadlines at the outset of your relationship with the bookkeeper and hold them to these. Check in regularly to make sure they are on track and have everything they need to complete their tasks.

  1. They don’t let you see the books

A bad bookkeeper will want to keep you out of the know and will be unwilling to let you see the books. This is a major sign that they are hiding something, like mismanagement of your books, or worse – they could be stealing from you. If they become defensive or overly protective when you ask to see the books that is the time you must step in and seek transparency. Remember, with cloud accounting software like Xero transparency is always there and all parties can see the same live date using their own access. It becomes more difficult to hide bad work or blame someone else.

What you can do: Demand control of the books and take ownership of account login. If your bookkeeper puts up a fight or denies you access, seek an alternative bookkeeping solution. Such behaviour is not part of professional conduct of a certified bookkeeper.


  1. They don’t ask questions

You might think that bookkeeping is a repetitive, mundane chore that doesn’t require any sort of inquisitive thinking. But that’s wrong. A good bookkeeper is not afraid to ask questions and dig deep to find answers. This helps them identify problems and suggest costs cutting opportunities, find areas to improve on, which helps drive your overall goals of growing your business. If your bookkeeper never asks questions, do they care about your books or your business? Indifference will lead to missed opportunities to help your business.

What you can do: Ask your bookkeeper questions, challenge them, and request suggestions on how to cut costs.


  1. You question their work

Trust your gut – deep down you know when things are not right. If you don’t know what your bookkeeper is up to because you only hear from them after you’ve chased and chased again and you have no idea where your business is financially, then it’s time to take action right away. Similarly, you have that feeling that your bookkeeper is doing it wrong, or you’ve seen the same mistakes over and over again, then it’s time to find a new solution.

What you can do: Trust is important when working with your bookkeeper! After all you are sharing your business’ (and personal) most sensitive information with them. If you can’t trust them, you need to find someone you do.


In the end it all comes down to your bottom line. Are you happy with your current bookkeeping solution? Or do you need to review your approach and find a better solution?


Talk to our experienced team to find a trusted bookkeeper for your business, have less stress and gain clarity for yourself and your business.


Covid-19 Government Support Update September 2020

On 25th September the government announced further Covid-19 support for employees and businesses. Below is our summary of the support schemes coming up.

Talk to us if you need help with claiming the support or making a plan for the future of your business – our team is here to support you in any way we can.


Job Support Scheme

A new Job Support Scheme will be introduced from 1‌‌ November to protect jobs where businesses are facing lower demand over the winter months due to coronavirus (COVID-19). The scheme will run for six months.

Employers will continue to pay the wages for the hours staff work. For the hours not worked, the government and the employer will each pay one third of their usual wages (capped at £697.92 per month). Employers will need to meet their share of the pay for unworked hours, and all employer National Insurance contributions and statutory pension contributions, from their own funds. This means that employees will receive at least two thirds of their usual wages for the hours not worked.
To be eligible, employees must:  

  • be registered on PAYE payroll on or before 23 September 2020. This means a Real Time Information (RTI) submission notifying payment in respect of that employee must have been made to HMRC on or before 23 September 2020

  • work at least 33% of their usual hours. The government will consider whether to increase this minimum hours threshold after the first three months of the scheme.

Full details are available here: Job Support Scheme factsheet.

The Job Support Scheme will be open to employers across the UK even if they have not previously applied under the Coronavirus Job Retention Scheme (CJRS) which ends on 3‌1‌‌ ‌‌October. The Job Support Scheme will start from 1‌‌ November and employers will be able to claim in December. Grants will be paid on a monthly basis.

The scheme will operate in addition to the Job Retention Bonus. Businesses can benefit from both schemes in order to help protect viable jobs.


Job Retention Bonus

The Job Retention Bonus is a one-off payment to employers of £1,000 for every employee who they previously claimed for under the Coronavirus Job Retention Scheme, and who remains continuously employed through to 31 January 2021. Eligible employees must earn at least £520 a month on average between the 1 November 2020 and 31 January 2021. Employers will be able to claim the Job Retention Bonus after they have filed PAYE for January and payments will be made to employers from February 2021.

More details on Job Retention Bonus can be found here.


SEISS Grant Extension

The government is continuing its support for millions of self-employed individuals by extending the Self-Employment Income Support Scheme (SEISS) grant. Self-employed individuals and members of partnerships who are eligible for the SEISS and are actively continuing trading but are experiencing reduced demand due to coronavirus (COVID-19), will be eligible for a further SEISS grant to provide support over the winter months.

The first grant will cover a three-month period from the start of November 2020 until the end of January 2021. It will be a taxable grant to cover 20% of average monthly trading profits, paid out in a single instalment covering three months’ worth of profits, and capped at £1,875 in total.

An additional second grant, which may be adjusted to respond to changing circumstances, will be available for self-employed individuals to cover the period from February to the end of April – ensuring our support continues right through to next year.

More information will be published in due course but in the meantime the current fact sheet has all the details.


VAT Deferral New Payment Scheme

If you deferred payments that were due between 20 March and 30 June 2020, then these payments need to be made to HMRC by 3‌1‌‌ ‌‌March 2021. Employers can use the New Payment Scheme to spread these payments over equal instalments up to 3‌1‌‌ ‌‌March 2022. Alternatively, they can make payments as normal by 3‌1‌‌ ‌‌March 2021 or make Time To Pay arrangements with HMRC if they need more tailored support.


New Self Assessment Self-Serve Time To Pay Scheme

If you deferred paying your July 2020 Payment on Account, you will need to pay the deferred amount, in addition to any balancing payment and first 2020/21 Payment on Account, by 3‌1‌‌ ‌‌January 2021. This may be a larger payment than you usually pay in January.

If you are unable to pay your Self-Assessment (SA) bill in full by 31‌‌ January 2021, you can set up a Time to Pay payment plan of up to 12 months online without speaking to us. If employers have SA tax debts of up to £30,000, they will be able to access this Time to Pay facility through GOV‌.UK and will get automatic and immediate approval. If their SA debts are over £30,000, or they need longer than 12 months to repay their debt in full, they will still be able to use our Time to Pay arrangement by calling HMRC.


Other business support schemes:

Changes to CJRS – what you need to do from 1‌‌ October.

From 1‌‌ October, HMRC will pay 60% of usual wages up to a cap of £1,875 per month for the hours furloughed employees do not work. Employers will continue to pay furloughed employees 80% of their usual wages for the hours they do not work, up to a cap of £2,500 per month. Employers will need to fund the difference between this and the CJRS grant themselves.

The caps are proportional to the hours not worked. For example, if an employee is furloughed for half their usual hours in October, employers are entitled to claim 60% of their usual wages for the hours they do not work, up to £937.50 (half of £1,875 cap). Employers must still pay their employees at least 80% of their usual wages for the hours they don’t work, so for someone only working half their usual hours they’d need to pay them up to £1,250 (half of £2,500 cap), funding the remaining portion themselves.

You will also continue to pay furloughed employees’ National Insurance and pension contributions from your own funds.

6 Top Tips on Keeping Your Xero Tidy

Now is the perfect time to go through your Xero and give it a good tidy up.

We recommend checking your contacts, bank reconciliation and bills regularly to avoid errors and headaches. It will save you hours later trying to figure out what has gone wrong.

1. Contacts 

Is your Contacts list getting out of control? It is long and you have a few names for the same contact but you can’t remember which one you used last time?

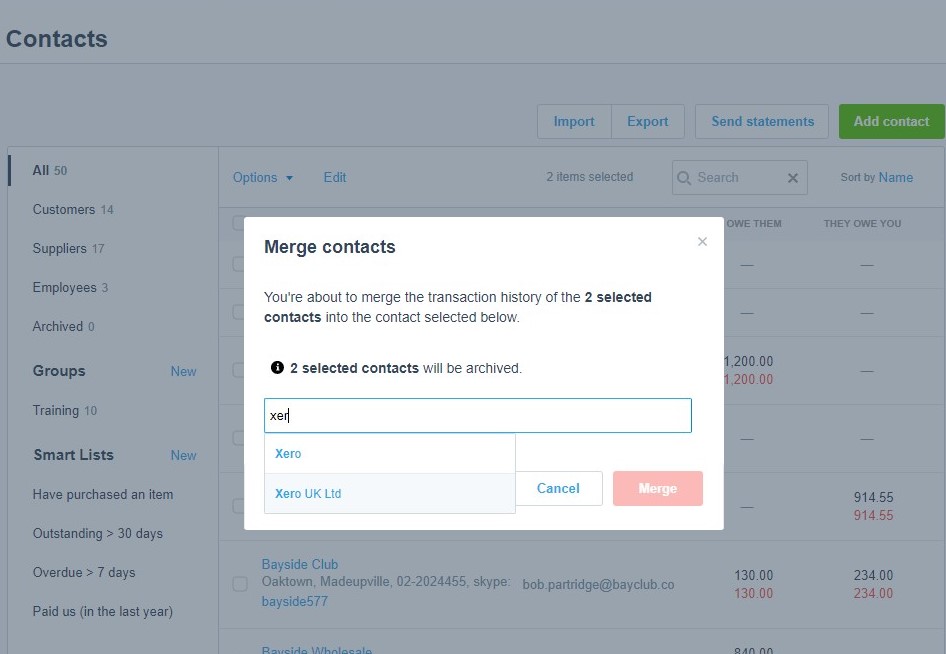
It is good practice to do a little housekeeping on your Contact list in Xero. Some could be merged if they are duplicates. Maybe some are so old or even erroneous, and they could be archived.

How to merge a contact:

  • From the Contacts menu click the one or more contact you wish to merge into another contact
  • Click Options at the top and select Merge
  • In the Merge Contacts box select the contact that you want to merge to – this is the contact that will remain – choose Merge.

To Archive unwanted contacts, follow the above but in the Options menu select Archive.

Keep your accounts data clean and reduce the risk of missing something, for example if you look up an invoice in one account, only to find later it was on duplicate account.

2. Credit notes

Do you have unallocated credit notes showing in Bills Awaiting Payment screen? Where possible these should be allocated against invoices or cash refunds allocated to them.

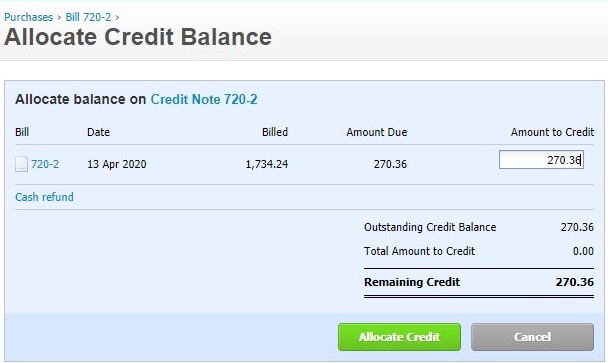
To allocate credit note against invoice:

  • open the credit and to Credit Note Options menu.
  • select Allocate Credit
  • enter the credit amount against correct invoice
  • Click Allocated

3. Duplicate purchases invoices

It is a good practise to check if any outstanding purchases invoices in Awaiting Payment have been duplicated. Sometimes you can write the invoice number incorrectly or use purchase order number instead of the invoice number which would result in the same invoice entered twice. If that happened Xero won’t alert you that the invoice is a duplicate.

To quickly check if you have any errors:

  • go to Bills to Pay and select All
  • Search supplier name
  • Review outstanding invoices, amounts and dates

If you think you have paid the invoice, but it is still showing as outstanding you might have reconciled the payment as spend money and not as invoice payment. In this case, search for supplier or amount within the bank account transactions.

4. Outstanding bank items

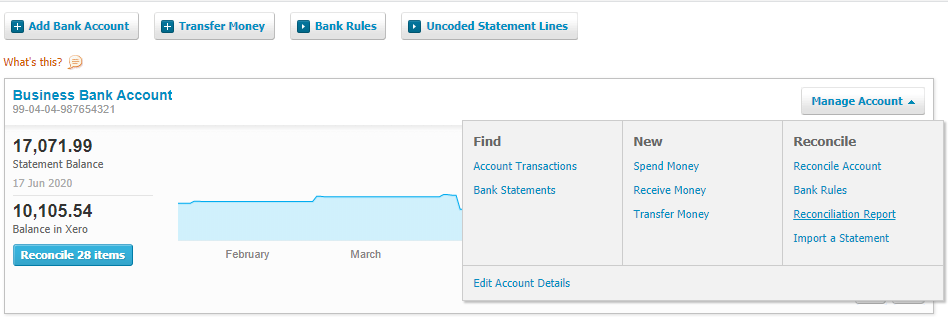
With direct bank feeds, managing bank account transactions is fast and pain free. But sometimes Xero and bank statement balances do not match. There can be numerous reasons for this, for example unreconciled transactions entered in Xero, missing statement lines, duplicated transactions or errors recording transfers between accounts. See our article 5 Mistakes to Avoid When Reconciling Bank Transactions in Xero.

To check if your bank account balance and the balance in Xero match review the Bank Reconciliation Report.

5. Xero files

If you are using Xero files you can upload and store any document you need for easy access from anywhere. This will help you declutter your office and keep things in one place. Create a separate folder for bank statements, back up documents, supplier statements, HMRC items etc. All Standard and above users can see Xero Files and it is a perfect way to share documents securely with your team or accountant.

6. Bank rules

Are you using bank rules? Set up correctly Bank Rules will save you time when entering recurring transactions such as bank interest or direct debits where a bill is not entered. You need to set up the criteria accordingly, so the correct transactions are identified. For each bank statement line that matches a rule, Xero suggests a transaction using the condition you have set. See our Bank Rules in Xero article for more details.


While Xero is intuitive and easy to use it is not always simple. There are areas we find users make mistakes and find themselves stuck not knowing how to set Xero straight. If you need help fixing Xero, we are here to help. Give us a ring for a friendly chat today.

Coronavirus Job Retention Scheme – how to claim

Here are the links on what and how to claim for Coronavirus Job Retention Scheme.

1. Check if you can claim for your employees’ wages through the Coronavirus Job Retention Scheme

2. Work out 80% of your employees’ wages to claim through the Coronavirus Job Retention Scheme

3. Claim for wages through the Coronavirus Job Retention Scheme


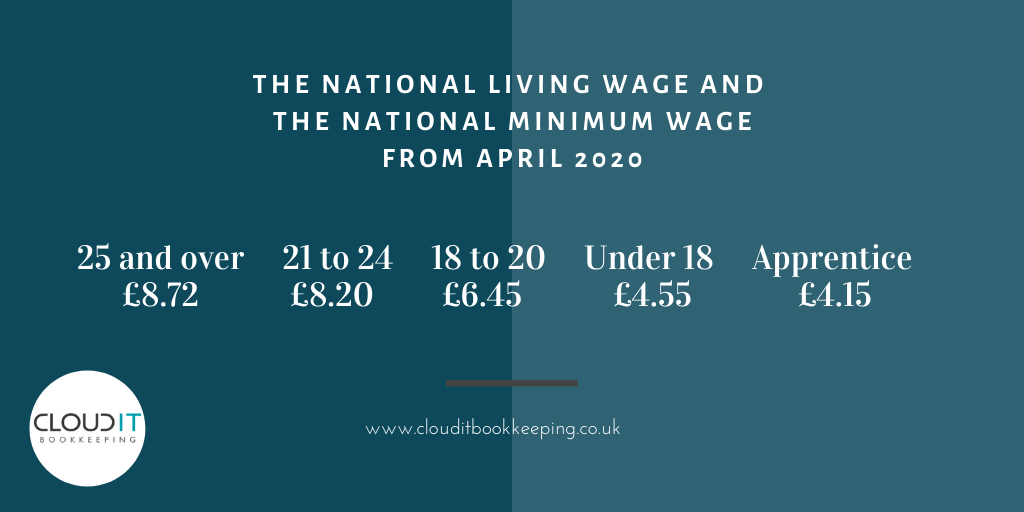
National Minimum Wage from April 2020

The new National Minimum Wage and National Living Wage rates coming into effect in April 2020. Here are the details of the new rates which are available on HMRC website.


Tax Filing and Payment Deadlines

Meeting your tax filing and payment duties

For any company or individual, meeting their deadlines when it comes to filing and payment of taxes to the government is essential. It is the responsibility of every business to meet their deadlines without fail, as missing these will trigger the risk of getting a penalty. Here are some Filing and Payment deadlines to help you keep up with your duties.

Self-Assessment

 Self-Assessment is a system HM Revenue and Customs (HMRC) uses to collect Income Tax. Tax is usually deducted automatically from wages, pensions and savings. People and businesses with other income must report it in a tax return. If you need to send one, you fill it in after the end of the tax year (5 April) it applies to.

 Deadlines:

 Registering and Filing Deadlines:

HMRC must receive your tax return and any money you owe by these deadlines following the end of the tax year:

  • Register for Self-Assessment: 5 October
  • Paper Tax returns: Midnight 31 October
  • Online Tax returns: Midnight 31 January

Payment Deadlines:

The deadlines for paying your tax bill are:

If you prefer to pay regularly throughout the year, you can use a budget payment plan.

Penalties:

You’ll get a penalty if you need to send a tax return and you miss the deadline for submitting it or paying your bill. You’ll get a penalty of £100 if your tax return is up to 3 months late. You’ll have to pay more if it’s later, or if you pay your tax bill late. You’ll also be charged interest on late payments.

PAYE

Any employer would normally operate PAYE as part of their payroll. PAYE is HMRC’s system to collect Income Tax and National Insurance from employment. You do not need to register for PAYE if none of your employees are paid £118 or more a week, get expenses and benefits, have another job or get a pension. However, you must keep payroll records.

Filing: 

When paying your employees through payroll you also need to make deductions for PAYE. The PAYE deductions will be filed to HMRC through RTI (Real Time Information) submission every month on the day of paying your employees.

Payments and deductions:

You’ll be able to view what you owe HMRC, based on your reports. You then have to pay them, usually every month.

You must pay your PAYE bill to HMRC by:

  • 22nd of the next tax month if you pay monthly
  • The 22nd after the end of the quarter if you pay quarterly – for e.g. by 22nd July for 6th April- 5th July quarter.
  • If you pay by cheque through the post deadline is 19th of the month.

CIS

 Under the Construction Industry Scheme (CIS), contractors deduct money from a subcontractor’s payments and pass it to HMRC.

Filing:

 You must tell HMRC each month about payments you’ve made to subcontractors through your monthly return. You do not have to file a return for the months when you made no payments to subcontractors, but you must tell HMRC that no return is due.

Deadlines:

 Send your monthly returns to HMRC by the 19th of every month following the last tax month. For example, if you’re making a return for the tax month of 6 May to 5 June, it must reach HMRC by 19th June.

VAT

 You must register your business for VAT with HMRC if its VAT taxable turnover is more than £85,000* (*VAT registration threshold in 2020).

 You usually submit a VAT Return to HMRC every 3 months. This period of time is known as your ‘accounting period.’

The VAT Return records things for the accounting period like:

  • your total sales and purchases
  • the amount of VAT you owe
  • the amount of VAT you can reclaim
  • what your VAT refund from HMRC is

You must submit a VAT Return even if you have no VAT to pay or reclaim.

Deadlines:

 The deadline for submitting the return online and paying HMRC are usually the same – 1 calendar month and 7 days after the end of an accounting period. You need to allow time for the payment to reach HMRC’s account.

Pay your VAT bill:

 You must pay VAT to HMRC electronically, for example through direct debit or internet banking. Most businesses are not allowed to pay by cheque.

Corporation Tax

Corporation tax or company tax, is a direct tax imposed by a jurisdiction on the income or capital of corporations or analogous legal entities, foreign corporations who have a permanent establishment in the country, or corporations deemed to be resident for tax purposes in the country.

Rate:

Corporation Tax main rate is 19% from the year starting on 1 April 2017. To check the current corporation tax rate click here.

Deadlines:

The deadline for your tax return is 12 months after the end of the accounting period it covers. You’ll have to pay a penalty if you miss the deadline.

There’s a separate deadline to pay your Corporation Tax bill. It’s usually 9 months and 1 day after the end of the accounting period.

Ways to pay:

Make sure you pay HMRC by the deadline applicable. You’ll be charged interest and may have to pay a penalty if your payment is late.

The time you need to allow depends on how you pay. You can no longer pay at the Post Office.

Same or next day:

  • online or telephone banking (Faster Payments)
  • CHAPS
  • by debit or corporate credit card online
  • at your bank or building society

You need a paying-in slip from HMRC to pay at a bank or building society.

3 working days:

  • Bacs
  • Direct Debit (if you’ve set one up with HMRC before)
  • by cheque through the post

5 working days:

  • Direct Debit (if you have not set one up with HMRC before)


If the deadline falls on a weekend or bank holiday, make sure your payment reaches HMRC on the last working day before (unless you’re paying by Faster Payments or by debit or credit card).

You can find more information on how to pay HMRC here: https://www.gov.uk/topic/dealing-with-hmrc/paying-hmrc

5 Reasons You Need a Cash Flow Forecast

Cash is the lifeblood of all business, especially for start-ups and small enterprises. We all know the phrase “cash is king”.

If a business runs out of cash and is not able to obtain new finance, it will become insolvent. It is essential that business owners forecast what is going to happen to cashflow to make sure the business has enough to survive. With accounting tools currently available , it is no excuse to claim that you didn’t see a cash flow crisis coming.

What is Cash Flow?

Cash flow is the net amount of cash moving into and out of a business at any given time. The key word here is “time,” as the amount of money moving in and out of your business can only really be understood through a given timeframe. Most businesses track their cash flow on a month-to-month basis.

What is Cash Flow Forecasting?

A cash flow forecast is a projection of an organisations future financial position based on the anticipated payments and receivables. The process of deriving a cash flow forecast is called cash flow forecasting.

A cash flow forecast estimates how much money will flow in and out of your business at any given time. This means it includes all your projected revenues and excludes all your non-cash expenses and costs. A cash flow forecast typically covers a yearly period, though can be made for any time frame—a week, a month, or a year.

5 Reasons You Need a Cash Flow Forecast

Projecting your cash flow can help you plan for the future, avoid unexpected shortfalls and even qualify for a small business loan.

1. Avoid cash flow problems

Unexpected shortfalls can be crippling, and it may take months (if not longer) to recover. Negative cash flow can creep up on you if you don’t consistently track the cash coming in and going out of your business. Fortunately, shortfalls are often avoidable with a bit of foresight.
Projecting your cash flow will help you identify and plan for market swings, seasonal fluctuations and other business patterns that can lead to unpredictable cash flow. Forecasting can even help you visualize cash flow trends with the help of automatically generated charts and graphs.

2. Anticipate the impact of upcoming changes

Does your business plan to purchase new equipment? Launch a new product? Cash flow projections allow you to gain a complete picture of the ripple effect that these types of changes will have on your cash flow.
When your finances are synced up with an online cash flow management tool, cash flow projections are automatically generated based on future invoices, bills due and payroll. You can then create “what if” scenarios, such as buying new equipment. Forecasting shows you how the cost will affect your bottom line, along with the potential increase of revenue generated by the new machine.

3. Optimize the timing of accounts payable and receivable

Many avoidable cash flow issues are often a simple matter of timing. Significant delay time between invoicing your customers, or shipping out products, and getting paid can cause unnecessary strain on your cash flow.
Cash flow projections that are based on your financial history can help you anticipate when you’ll be paid for your services or products. This allows you to stagger or otherwise adjust outgoing payments to your vendors accordingly. This will help avoid putting yourself in the uncomfortable position of not being able to pay your suppliers, or worse, your employees.

4. Better decision making

Another benefit of being able to run different scenarios through your cash flow forecast is that you can make better operational decisions.
Perhaps you have a choice between additional staff or investment in equipment and you aren’t sure which decision is going to be most profitable for your business in both the short and long term.
Forecasting the different options will give you the information you need to make these decisions with confidence and assurance that you know what impact they will have on your business.

5. Prove You Can Pay Back the Loan You Requested

When you apply for a small business loan, lenders will examine your cash flow history in an attempt to answer one key question: can this borrower pay back the loan they’re requesting?

Asking for a loan of any amount without showing your plan for paying it back is a good way to land in the rejection pile. This is especially true if your current cash flow won’t clearly cover all of your regular operating expenses — plus your loan payment.
If you find yourself in this situation, cash flow projections can help strengthen your case by showing the lender exactly how you plan to use their funds to get to a place where you can easily make loan payments. This type of forecasting allows you to hand over a road map that can instil a lender with the confidence they need to approve your loan.


By maintaining a cash flow forecast, you get a significantly more accurate read on the financial health of your business. Furthermore, you’ll be prepared for times when money might be tight and identify certain patterns in your cash flow fluctuations. Perhaps most important with a cash flow forecast you’ll be able to relieve the anxieties of the unknown and sleep more easily knowing that you’re prepared for what’s to come. If you need any help with your business’s Cash Flow Forecast, get in touch with us at Cloudit Bookkeeping – we are always happy to help.

Why should your business set a budget?

Time and money are the most valued resources for all individuals and organizations. Efficient and effective use of these resources requires planning and sometimes creativity, especially if you are starting out or are a small business.

Planning on how to use your time and money in your business alone is not enough, as you and I already know. Best intentions not always result in actions and sticking to the plan.  That’s where we need control to ensure that plans are carried out.

That’s where a budget really helps.

A budget is a tool that managers use to plan and control the use of scarce resources. A budget is a plan showing the company’s objectives and how management intends to acquire and use resources to attain those objectives.

Budgeting is the process of creating a plan to spend your money. It is a financial plan for the future concerning the revenues and costs of a business. However, a budget is about much more than just financial numbers.

Budget for Business:

Budgets are an integral part of running any business efficiently and effectively.

Once a business is established, budgeting becomes a regular task that normally occurs on a quarterly and/or annual basis, where the past quarter or year’s budget is reviewed, and budget projections are made for the next three or even five quarters or years. The basic process of planning a budget involves listing the business’s fixed and variable costs on a monthly basis and then deciding on the allocation of funds to reflect the business’s goals.

Businesses often use special types of budgets to assess specific areas of operation. A cash flow budget, for instance, projects your business’s cash inflows and outflows over a certain period of time. Its main use is to predict your business’s ability to take in more cash than it pays out.


Why Does Your Business Need a Budget?

Without a budget, you may not know how your business is performing. A budget provides an accurate picture of expenditures and revenues and should drive important business decisions such as whether to:

  • Increase marketing
  • Cut expenses
  • Hire staff
  • Purchase equipment
  • Improve efficiencies in other ways

A comprehensive budget will also be a definite requirement for obtaining business loans from financial institutions or seeking equity funding from investors.

Budgeting is always helpful since it helps you to track revenue and expenses and manage cash flow. But creating a budget that does nothing more than set spending limits can damage a small business by preventing it from reacting to market conditions. A flexible budget helps you to adjust spending, increase marketing to expand sales, react to an unexpected drop in revenues and otherwise operate your company using real-time data to keep it on track.

Planning

A budget is a planning tool necessary for building a framework for your business and its finances. Combining past trends with realistic forecasts for the year, a budget provides a detailed view of assets, realistic revenue expectations, and how those balance against your anticipated expenses.

Budgets also help with setting goals and establishing priorities. A budget should detail where funding will come from to execute new strategies and how much revenue can be generated by executing the strategies successfully. The line items that command the most funding or generate the most revenue typically are high-priority items, and that can serve as a good reminder of your overall strategy when making decisions.

Evaluation

In addition to being an important part of the planning process, budgets are necessary for evaluating the performance of your company over the course of the year. Part of budgeting responsibly is tracking actual revenue and expenses and comparing them to what was budgeted. This helps to assure that your business is sticking to its plans but budgeting also offers an important means of identifying problems and opportunities.

Financing

A history of writing sound, detailed budgets and sticking to them can help show lenders or potential investors that you know how to develop a business plan and make it work. Lenders and investors certainly will want to dig much more deeply into your finances and history, but if they don’t see evidence of strong budgeting practices, that might be enough of a red flag to turn them away.

If you are opening a new business and have little or no history, you need to make up for that lack of track record with detailed support for your budget. This means doing research into the marketplace and showing how past trends or perhaps a void in the industry supports the numbers you are presenting. This kind of attention to detail can help you gain serious consideration from lenders or investors.

Benefits of a business budget:

There are a number of benefits of drawing up a business budget, including being better able to:

  • Manage your money effectively
  • Allocate appropriate resources to projects
  • Monitor performance
  • Meet your objectives
  • Improve decision-making
  • Identify problems before they occur – such as the need to raise finance or cash flow difficulties
  • Plan for the future
  • Increase staff motivation

Budgeting in a business has benefits and consequences that go beyond the financial dimension and have more to do with business management in general.

Consider the following additional benefits of a budgeting process:

  • Budgeting forces managers to do better forecasting. Managers should be constantly checking the business environment to spot changes that will impact the business. Vague generalizations about what the future may hold for the business are not good enough for building a budget. Managers must put their predictions into definite and concrete forecasts.
  • Budgeting motivates managers and employees by providing useful measures for evaluating performance. The budgeting process can have a good motivational impact by involving managers in the budgeting process and by providing incentives to managers to strive for and achieve the business’s goals and objectives.
  • Budgeting can assist in the communication between different levels of management. Putting plans and expectations in black and white minimizes confusion and creates a common language. Well-crafted budgets can undeniably help the communication process.
  • Budgeting is essential in writing a business plan. New businesses need to present a convincing business plan when raising capital. Because these businesses may have little or no history, the owners must demonstrate convincingly that the company has a clear strategy and a realistic plan to make profit. A clear, realistic budget forecast is an essential part of a business plan.

Creating a business budget will make operating your business easier and more efficient. A business budget can also help to make sure that you’re spending money in the right places and at the right time to stay out of debt. Cloudit Bookkeeping can help you put your budget in place and assist you with planning and re-evaluating your forecasts. Get in touch with us to find out more.

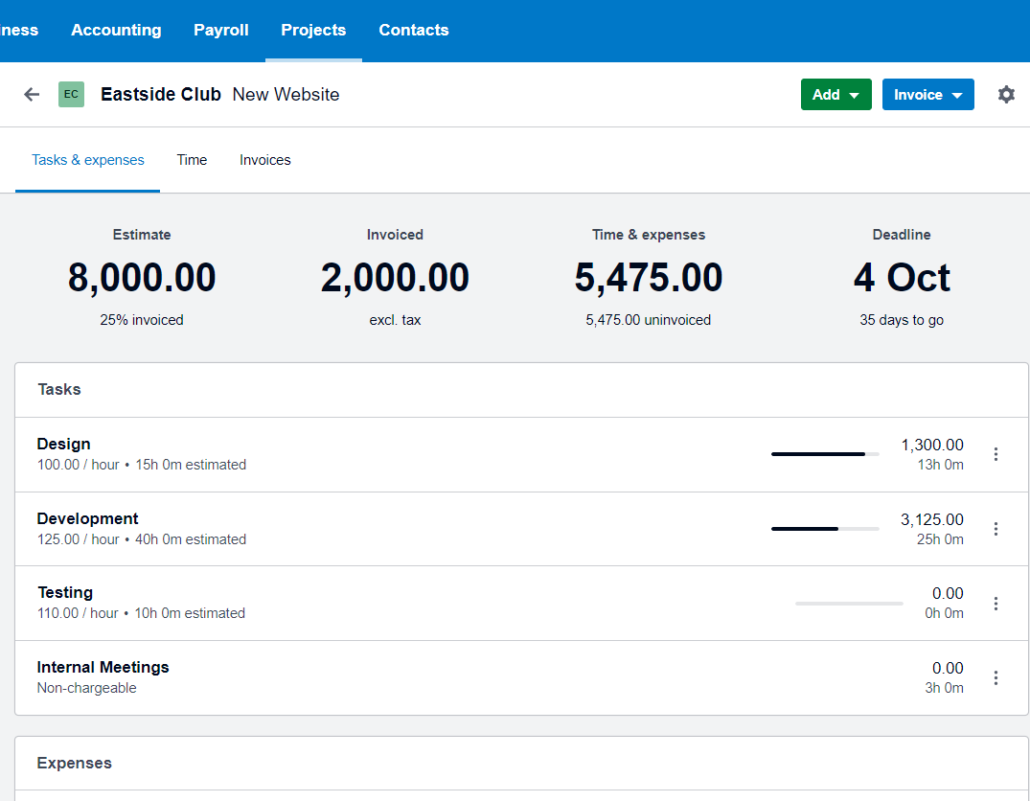
Are Your Jobs Profitable? Why Track Project Profitability With Xero

If you’re in the business of providing a service, you are likely to offer up your time and expertise to clients anywhere, throughout the day. Whether over the phone, via email or in person, any time spent on one client’s job is less time spent on something else and is therefore a cost to you. This cost can easily be missed if you’re relying on spreadsheets, notebooks or even scraps of paper. You might also have costs associated with delivering your service to your client which you want to recharge to them, and it might take a while to go back through the records and put these costs together.

Good news is – Xero offer Projects module to solve these problems in an easy and straightforward way within the accounting software. It comes with the mobile app, so tracking is easy and project accounting is a breeze.

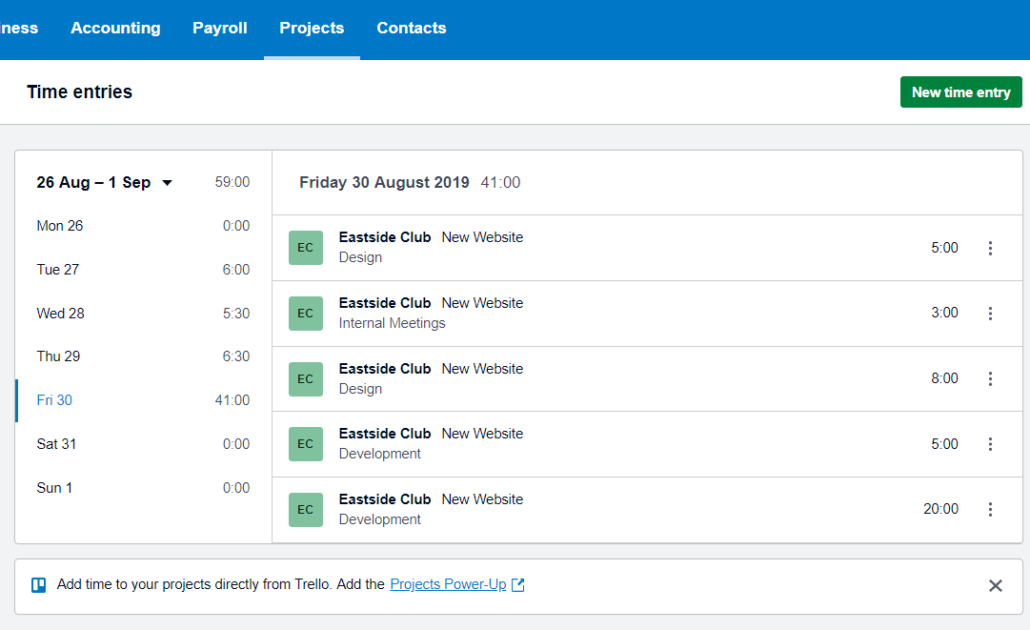
Xero Projects is the simple way to track the time and money you spend on each job, allowing you to focus on the right work, improve efficiency and drive profitability.

With the Projects mobile app, you can add a project as soon as you start it, from wherever you may be. That means you can stay on top of your project expenses as they come in and record your time as you go about your business.

Why should you track your project profitability in Xero? Here are just a few reasons for using Xero Projects:

  • Have everything in one place, accessed with one Xero login
  • Intuitive, simple to activate and use
  • Supports fixed price, time and expenses invoicing
  • Assign your actual invoices, bills and bank transactions to project
  • Visibility across all jobs and how they’re tracking
  • Monitors budgets and job costs
  • Out-of-the-box reporting
  • Timesheet insights and reporting
  • Real-time view of all your Projects in one place
  • Monitor job costs from day to day to stay on track

Get your billing right every time

Track time, enter receipts and expenses, and record any deposits against each project so you can bill accurately on time and don’t miss anything.

Invoice the way that suits you

Create fixed price, time and materials, or progress payment invoices. Details can be uploaded automatically, saving you time and avoiding errors.

Gain insights you need to succeed

Monitor and track project performance with up-to-the-minute reports on time and costs to help you keep to budget and decide when to invoice.

Review actuals against budget

Add estimates for project costs to the project budget and monitor it to make sure you’re turning a profit.

Capture all of your job costs

Assign bills and expenses, and record deposits against each project so you can invoice accurately and on time.

Quote based on what’s gone before

Use the figures and reports from previous projects so you know what to realistically quote next time round.


Profitability and time are the linchpin of service businesses. Xero Projects is geared for businesses with straightforward time and job cost tracking needs such as design and web design agencies, marketing agencies, consultancies, and even businesses in construction industry. It will really appeal to those still fiddling around in spreadsheets, or who find most project management software too complex. If you need help with using Xero Projects, we, at Cloudit Bookkeeping will be happy to help you.


Record Keeping Under MTD

Making Tax Digital for VAT requires VAT registered businesses with taxable turnover above the VAT registration threshold to keep records in digital form and file their VAT Returns using software.

It is increasingly common for business records and accounts to be kept digitally, in a software program on a computer or tablet, or in a smartphone application, or maintained through such a device and stored using a cloud-based application.

The difference under Making Tax Digital is that the software which businesses use must be capable of keeping and maintaining the records specified in the regulations, preparing their VAT Returns using the information maintained in those digital records and communicating with HMRC digitally through the Application Programming Interface (API) platform.

If your digital records are up to date, software will be able to collate and prepare your return for you. It will then show the return to you and ask you to declare that it is correct and confirm that you want to submit it to HMRC. Once you have submitted your return you will receive confirmation through your software that it has been received.

What records you must keep and how to keep them if you’re registered for VAT

Records you must keep

The basic rule is that you must create and keep normal business records. You do not have to keep records in a set way and most bookkeeping and computer systems will meet this requirement.

Apart from keeping business records and the special requirements, HMRC asks that records are complete, up to date, and allow you to calculate correctly the amount of VAT that you have to pay or can claim from them.

Special records for VAT

There are 2 records that are specifically required for VAT. These are:

  • the VAT account, in many cases this will be based on a routine business record of VAT you owe or can claim
  • a VAT invoice for supplies to other VAT-registered businesses, a ‘VAT invoice’ is just the term for an invoice which contains some information required by the VAT rules, most commercial invoices will already hold the right information

Business records

VAT law requires you to keep all your business records. The view of business records is wide and will include:

  • annual accounts, including profit and loss accounts
  • bank statements and paying-in slips
  • cash books and other account books
  • credit or debit notes you issue or receive
  • documentation relating to dispatches and acquisitions of goods to or from EU member states
  • documents or certificates supporting special VAT treatment such as relief on supplies to visiting forces or zero rating by certificate
  • import and export documents
  • orders and delivery notes
  • purchase and sales books
  • purchase invoices and copy sales invoices
  • records of daily takings such as till rolls
  • relevant business correspondence
  • VAT account

What a business record is will depend on the type of business you run. You’ll always have to keep a VAT account and copies of invoices, but some of the other records may not be a normal record in your business. If that’s the case, you do not have to keep such a record just for VAT. But equally, some businesses will create additional business records, and these must be kept and produced to HMRC when you’re asked.

Keeping records

Generally, you must keep all your business records for VAT purposes for at least 6 years. Records that you use for other tax purposes may need to be kept for longer periods.

If the 6-year rule causes you serious storage problems or undue expense, or you need advice on records for other types of tax, then you should consult VAT general enquiries in HMRC portal. HMRC may be able to allow you to keep some records for a shorter period.

Additional records you might have to keep

HMRC may direct some businesses to keep additional records. This is where they have reasonable grounds to believe that such records might help them identifying supplies on which VAT is at particular risk of going unpaid. This will most commonly arise with supplies of mobile phones and computer chips but is not limited to these types of supplies. Failure to comply with one of these directions can result in a financial penalty.

You have a right of appeal against the issue of a direction and against the imposition of any penalty for non-compliance.

Keeping records on your computer

It’s common for business records and accounts to be kept on a computer and there are no special VAT rules about using a computer.

Failing to keep or produce records

There’s a financial penalty for failure to keep or produce the records required by law.

You can request a review of any penalty or appeal to an independent tax tribunal.


Digital record-keeping

All VAT registered businesses must keep and preserve certain records and accounts. Under Making Tax Digital, some of these records must be kept digitally within functional compatible software. Records that are not specified in this notice, or that are not required to complete your VAT Return, do not need to be kept in functional compatible software.

Some software will record all your VAT records and accounts information. However, there are some records that by law must be kept and preserved in their original form either for VAT purposes or other tax purposes.

Example

A business receives an invoice and types selected data contained in the invoice into functional compatible software. They must still keep the invoice in its original form as the data in the functional compatible software is not a copy of the invoice.

If you deregister from VAT you will no longer need to keep digital records in functional compatible software, but you must retain your VAT records for the required period.

Functional compatible software

Functional compatible software is a software program, or set of software programs, products or applications, that must be able to:

  • Record and preserve digital records.
  • Provide to HMRC information and returns from data held in those digital records by using the API platform.
  • Receive information from HMRC using the API platform.

Digital links:

Data transfer or exchange within and between software programs, applications or products that make up functional compatible software must be digital where the information continues to form part of the digital records. Once data has been entered into software used to keep and maintain digital records, any further transfer, recapture or modification of that data must be done using digital links. Each piece of software must be digitally linked to other pieces of software to create the digital journey.

A ‘digital link’ is one where a transfer or exchange of data is made, or can be made, electronically between software programs, products or applications. That is without the involvement or need for manual intervention such as the copying over of information by hand or the manual transposition of data between 2 or more pieces of software.

HMRC also accepts that the following are digital links:

  • Emailing a spreadsheet containing digital records so the information can be imported into another software product
  • Transferring a set of digital records onto a portable device (for example, a pen drive, memory stick, flash drive) and physically giving this to someone else who then imports that data into their software
  • XML, CSV import and export, and download and upload of files
  • Automated data transfer
  • API transfer

Soft landing regarding digital links requirements

HMRC will allow a period of time, the “soft landing period”, for businesses to have in place digital links between all parts of their functional compatible software.

For the first year of mandation businesses will not be required to have digital links between software programs.

This means that if Making Tax Digital rules first apply to you from a:

  • VAT period starting on or after 1 April 2019 – you will have until your first VAT return period starting on or after 1 April 2020 to put digital links in place
  • VAT period starting on or after 1 October 2019 – you will have until your first VAT return period starting on or after 1 October 2020 to put digital links in place

During the soft landing period only, where a digital link has not been established between software programs, HMRC will accept the use of ‘cut and paste’ or ‘copy and paste’ as being a digital link for these VAT periods

Submission of information to HMRC

The submission of information to HMRC must always be through an API. While HMRC expects most businesses to use API-enabled commercial software packages both to keep digital records and file their VAT Returns, the following alternatives may be available.

Bridging software

This is a digital tool incorporating relevant Making Tax Digital APIs that is used to connect accounting software to HMRC systems. It allows the required VAT information to be reported digitally to HMRC, and for information to be sent digitally back to the business from HMRC.

API-enabled spreadsheets:

These are spreadsheets that incorporate relevant Making Tax Digital APIs. They can either:

  • combine with accounting software to submit the required VAT information digitally to HMRC, and allow information to be sent back to the business digitally from HMRC
  • be used to keep digital records and then directly submit the required VAT information digitally to HMRC.

Errors found in records

Where you find that your VAT records contain errors, you will need to correct them. This guidance only applies to declarations of UK VAT and doesn’t apply to VAT MOSS returns, as these contain declarations of VAT due in other EU member states. To correct errors in declarations of VAT due in other member states, you will need to follow the rules of the relevant EU member state.

If that advice does not fit your particular circumstances, you may need further help from HMRC VAT Helpline, or you may wish to consult your own tax adviser.

Where an error has led to a misdeclaration on a VAT return you’ve already sent to HMRC, you can always correct the error at a later point of time using HMRC links. If you deliberately fail to correct an under declaration of VAT, you may be liable to a penalty or even criminal prosecution.


The records listed must be kept, maintained and preserved in digital form. The exact way you must enter the information will depend on the software package. The API enabled spreadsheets can be used to keep digital records and then directly submit the required VAT information digitally to HMRC. Contact us at Cloudit Bookkeeping if you are unsure about how and what the records should be maintained and filed to HMRC and how to manage accounts digitally.
 

App of the Week – AutoEntry

With every task we do, we always ask the question “Is there a better way?” And with day to day bookkeeping – YES, there is! That’s why AutoEntry is our choice of The App of The Week.

AutoEntry simplifies your business’ bookkeeping. It eliminates manual data entry for accountants, bookkeepers and small businesses. It automates the extraction and processing of bills, invoices, expenses and receipts and inputs them directly into your accounting solution.

It is perfect for small and medium businesses across all industries where volume of invoices and receipts is high. No more manual data entry of invoices, receipts, bills or statements. Simply email, scan and upload, or snap with your mobile app.

Features

  • Submit Documents – No more manually inputting invoices, receipts or invoices. AutoEntry extracts the data you need and publishes to your accountancy package.
  • Data Security – AutoEntry employs best practice security policies including encryption across the platform.
  • Full Line Item Capture – AutoEntry captures full line items, including the description, unit price and quantity for each line, with verified accuracy.
  • Item line settings – Apply rules to allow AutoEntry to ‘remember’ specific line item descriptions, or certain words within a description.
  • Purchase Order Matching – AutoEntry syncs captured invoices to matching open purchase orders.
  • Document Storage – Once AutoEntry has posted your data, it creates digital records, so users no longer needs to hang on to large quantities of paper documents, with client data stored securely in the cloud.
  • Integrate seamlessly – It integrates with your accounts software including Xero, QuickBooks Online, Kashflow, Sage 50, Sage One, Reckon, Freeagent and others.

 Additional Features

  • Data extracted & verified – Remove manual errors and rely on quickly searching secured stored, digital copies.
  • Smart analysis – Easily submit invoices, expenses and receipts as you get them, on the go.
  • Auto-publish – Seamless automatic publishing of verified data into your account software.

 How it works

  • Capture and submit documents – Forward emails from suppliers, snap receipts on the mobile app, or scan and upload to the website.
  • Accurate, automated data extraction – Data is processed and verifies before applying remembered Supplier, Tax Code and Category rules.
  • Seamless integrations – The add-ons ensure the seamless automatic publishing of verified data in your account software

Benefits

  • Save time – No more manually inputting invoices, receipts, expenses or statements. AutoEntry extracts the data you need and publishes to your accountancy package.
  • Paperless – With data stored securely in the cloud, there’s no need to store, file, print and copy paper documents anymore.
  • Integrations – Seamless automatic publishing of verified data into your accounting software.
  • Mobile app – Submit invoices, receipts and expenses on-the-go via the mobile app for iOS and Android devices.                                                                                                                       

Pricing

Powered by AI, AutoEntry is becoming increasingly sought after, due to its accuracy, speed and impressive range of in-built features. And, as well as being the smartest solution out there, with its flexible, pay-as-you-use pricing plans, AutoEntry also offers the best value for money. Users only pay for the documents they upload onto the platform, as needed month by month. Adding more companies or employees incurs no extra fees, meaning the whole team can make use of the solution without any fuss or extra expense. Advanced pricing plans available for firms with a large volume of documents.

By using AutoEntry, your businesses gain the following benefits:

  • Reduce the time and cost spent on manual data entry
  • Eliminate human error
  • Improve service turnaround times
  • Submit receipts and invoices on-the-go with its mobile app
  • Drive employee engagement
  • Store data more securely in the cloud

 AutoEntry + Xero

AutoEntry works by capturing and analyzing details from paper documents, before posting this information into a user’s Xero account. By leveraging the solution’s in-built intelligence, the data is entered into the correct fields every time, so there’s no fuss or room for error. 


Getting started

  1. Log into your AutoEntry account and go to ‘Company Setting’
  2. Click on the ‘Integrations’ tab and select Xero

Link your Xero with AutoEntry so that when you Publish your receipts or statements, they will directly be uploaded into Xero.

 With AutoEntry, you can say goodbye to piles of paperwork and hours spent typing up data, and get back to what really matters, serving their customers and growing their business. If you need help with setting up AutoEntry or integrating it with Xero we, at Cloudit Bookkeeping, will be happy to assist you.